Skyline Peak Advantage 5 FIA
Skyline Peak Advantage 5 FIA
Does Skyline Peak Advantage 5 FIA make your top 3?
Our clients typically get 23% more income than their first quote.
About Product
Skyline Peak Advantage — Built for clients who want the largest immediate boost to their contract value. Advantage carries Skyline Peak has the exclusive Bailout Rider*, giving clients an out if declared rates ever fall below the contract's bailout threshold.
Bailout Rider: If Mountain Life declares an S&P 500 Cap Rate or Fixed Rate below the contract's bailout threshold, the owner may withdraw penalty-free rather than stay locked into a lower rate. The Bailout Rider benefit is only available during the Bailout Window, which begins on the Contract Anniversary or the first day of a new Index Term Period. Available only on Skyline Peak Advantage without the Premium Bonus.
Allocation Accounts
| Name | Type | Rates |
|---|---|---|
| 3-Year S&P 500 High Water Mark Participation Rate |
High Water Mark (Quarterly)
Triennial
|
45%
Participation
|
| 1-Year Fixed Account with Bailout |
Fixed
|
5.5%
Fixed
|
| 1-Year S&P 500 PTP Cap with Bailout |
Point to Point
Annual
|
12%
Cap
|
| 1-Year S&P 500 PTP Participation Rate |
Point to Point
Annual
|
65%
Participation
|
| 1-Year Nasdaq-100 PTP Cap |
Point to Point
Annual
|
11%
Cap
|
| 1-Year Nasdaq-100 PTP Participation Rate |
Point to Point
Annual
|
50%
Participation
|
| 1-Year Franklin Innovators 10% ER PTP Participation Rate |
Point to Point
Annual
|
100%
Participation
|
| 1-Year S&P 500 Daily RC 10% ER PTP Participation Rate |
Point to Point
Annual
|
100%
Participation
|
| 1-Year Nasdaq-100 Volatility Control 10% PTP Participation Rate |
Point to Point
Annual
|
100%
Participation
|
Surrender schedule
| Year | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Penalty | 9% | 8% | 7% | 6% | 5% |
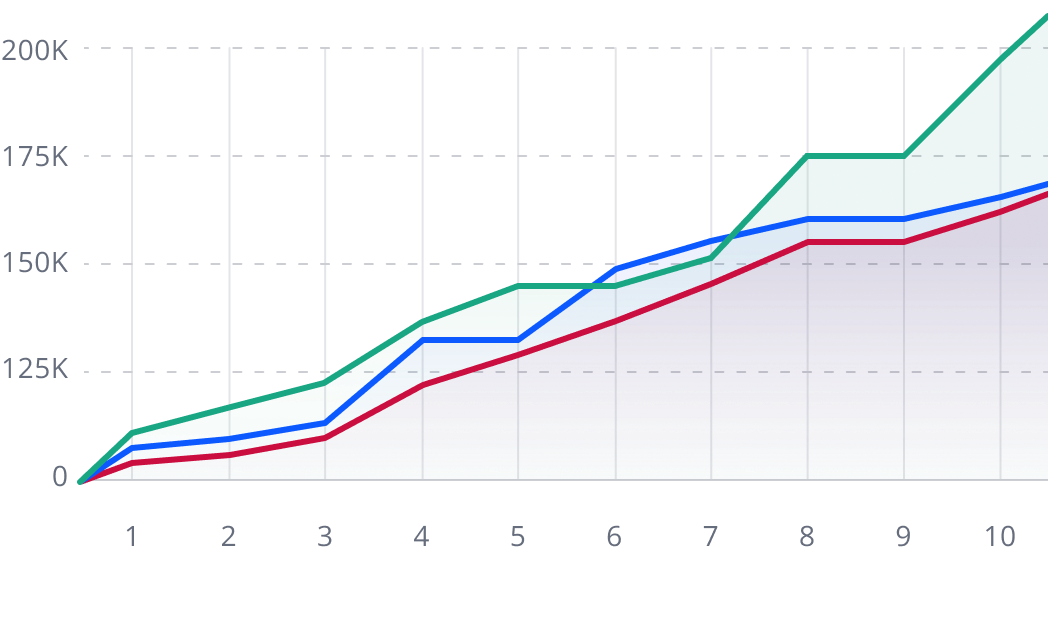
Hypothetical Projection
Riders
No Riders for Skyline Peak Advantage 5 FIA annuity.
Waivers
Bail-Out
If Mountain Life declares an S&P 500 Cap Rate or Fixed Rate below the contract's bailout threshold, the owner may withdraw penalty-free rather than stay locked into a lower rate. The Bailout Rider benefit is only available during the Bailout Window, which begins on the Contract Anniversary or the first day of a new Index Term Period. Available only on Skyline Peak Advantage without the Premium Bonus.
RMD
Required Minimum Distributions may be withdrawn penalty-free starting just 30 days after issue, in every contract year — including Year 1 — instead of the 10% free withdrawal limit.
Premium Notes
Issue Ages
0–90, with rates banded by age (0–80, 81–84, 85–90).
Minimum/Maximum Premium
$10,000 – $1,000,000 without Home Office approval.
Additional Premium
Additional premiums allowed in the first policy year, up to 100% of initial premium,
minimum $1,000, allocated to the Fixed Interest Account.
Withdrawal Provisions
WithdrawalsFree amount: beginning in Year 2, a flat 10% of full Contract Value (including any premium bonus) each year; unused amounts do not carry over.Minimum withdrawal: $500.Low balance: if a withdrawal would drop Contract Value below $2,000, the Company may treat it as a full surrender.RMD Friendly Required Minimum Distributions may be withdrawn penalty-free starting just 30 days after issue, in every contract year — including Year 1 — instead of the 10% free withdrawal limit.Market Value Adjustment (MVA)Standard MVA applies to withdrawals and surrenders in excess of the free withdrawal amount. Does not apply upon death of the owner.No surrender charge or MVA applies during the first 30 days of each subsequent surrender charge period, with written notice of options beforehand.
- A.M. Best B-